Competitive moat analysis is the structured evaluation that tests whether a company’s advantage produces persistent ROIC above WACC and the observable evidence that it will continue to do so. That distinction, persistent versus one-time, is what separates a real investment thesis from a gut feeling. Get it right and capital allocation, valuation, and M&A decisions all improve. Get it wrong and you are funding growth that destroys value.
TL;DR:
- A durable moat requires a consistent ROIC spread over WACC for at least five years, not just a single strong year that may be temporary.
- External data on win rates, customer retention, and pricing power carries more weight than internal claims when validating a company’s competitive advantage.
- Digital moats often hinge on usage-driven learning, integration depth, and switching costs, rather than the presence of proprietary data alone.
- Eroding moats and short-lived advantages should lead to a cautious approach, favoring harvesting or reallocating capital rather than aggressive growth.
- Regular, structured moat assessments with real-time competitor tracking and financial testing support better resource decisions and valuation accuracy.
How to measure a moat: ROIC, WACC, and economic profit
A moat is not a story. It is a number, or more precisely, a spread. Return on invested capital (ROIC) measures how efficiently a company turns capital into profit. Weighted average cost of capital (WACC) measures what investors require to supply that capital. When ROIC consistently exceeds WACC, the company is creating value, and McKinsey’s research on shareholder returns found that economic profit, the dollar spread between ROIC and WACC multiplied by invested capital, correlates with total shareholder returns more closely than earnings per share does.
Economic profit (EP) often beats ROIC as the headline metric for capital-light businesses. A software company with almost no invested capital can show a wildly high ROIC off a tiny denominator, which tells you little about the size or durability of the advantage. McKinsey’s analysis of capital-light business performance notes that small changes in invested capital can swing ROIC dramatically, while EP stays comparatively stable and decision-useful.
A few practical steps make this workable:
- Calculate ROIC and WACC for the trailing five to seven years, not just the most recent fiscal year.
- Plot the spread over time: a widening spread suggests a strengthening moat, a narrowing one suggests erosion.
- Build a simple sensitivity case: what happens to EP if margins compress by 200 basis points or invested capital doubles?
- Compare the spread against two or three direct peers, not against the market average.
Two quick checks catch the errors analysts make most often. First, when ROIC looks unusually high, check the invested capital base, a recent asset write-down or heavy buyback program can inflate ROIC without reflecting any operating improvement. Second, check whether the spread has held for multiple years or spiked in just one, since a single strong year tells you almost nothing about durability.
A practical moat-analysis workflow (step-by-step)
Testing a moat is a sequence, not a single calculation. Morningstar’s methodology lays out a version of this workflow that we have adapted into five repeatable steps for a strategy team or analyst to run on any business.
- Identify the mechanism. Name the specific source, cost advantage, switching cost, network effect, intangible asset, or efficient scale, rather than describing the advantage in vague terms like “strong brand.”
- Gather market-back evidence. Pull win rates against named competitors, customer willingness-to-pay data, retention and churn figures, and any pricing premium the company can sustain versus substitutes.
- Run the financial persistence test. Calculate the ROIC to WACC spread over five-plus years and check whether it is stable, widening, or narrowing.
- Evaluate reinvestment economics. Determine whether the company can redeploy capital at the same high return, or whether returns compress as it grows, which tells you how much of the advantage can scale.
- Rate trend and recommend action. Classify the moat as positive, stable, or negative in trend, then tie that rating to a concrete resource decision.
What you collect in step two matters as much as the math in step three. Win rate data, customer retention cohorts, documented pricing power, and any direct evidence of deal-winning differentiation all carry more weight than a company’s own claims about its advantages. McKinsey’s research on top economic performers found that the strongest performers are more likely to validate competitive advantage with external data and then use those findings to redirect R&D spending, geographic focus, and customer-segment priorities.
The output of this workflow should be a one-page moat scorecard: mechanism, supporting evidence, the financial test result, the trend rating, and a recommendation. That single page becomes the artifact a board or investment committee actually uses, rather than a forty-slide deck nobody rereads before the next quarterly review.
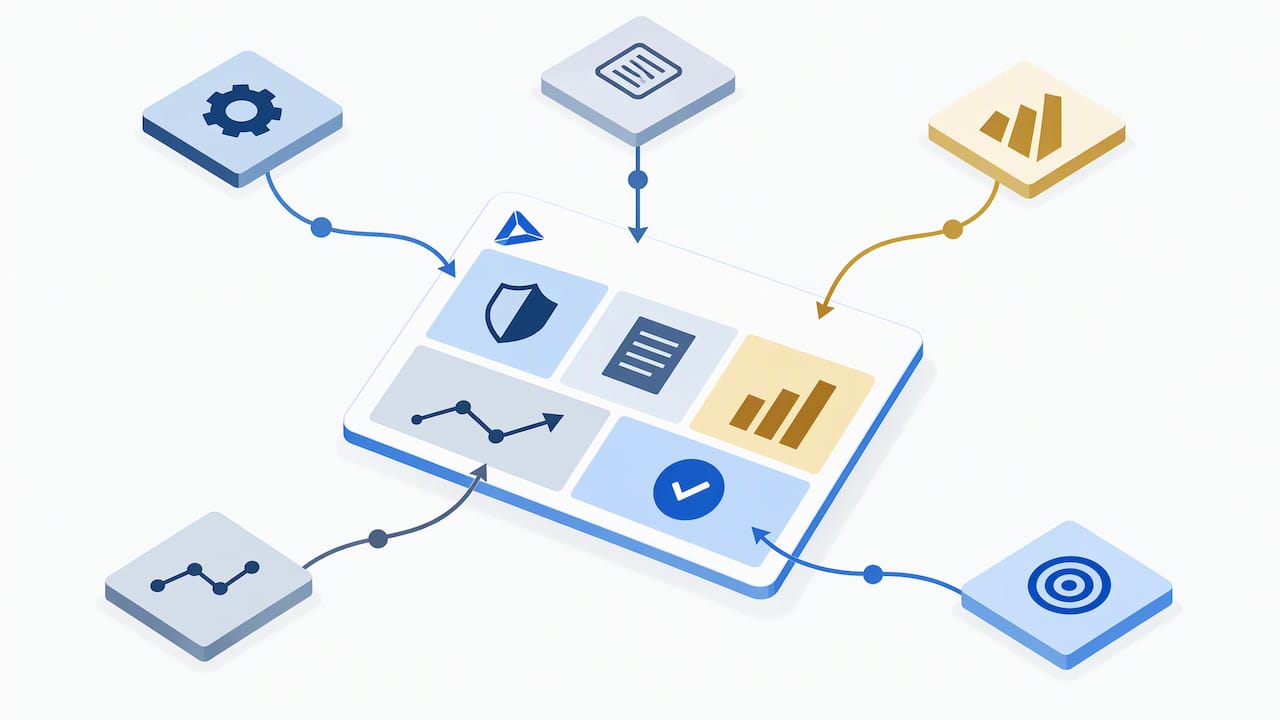
Pro Tip: Run the workflow on your two closest competitors alongside your own business, since a moat rating only means something in relative terms.
Assessing moats in AI and SaaS businesses
Digital businesses get misdiagnosed more than any other category, mostly because founders and analysts mistake a feature for a moat. Proprietary data, by itself, is rarely a defensible advantage. Wharton’s research on scaling and moats points to a more useful test: does usage actually improve the product, and do integrations create real switching friction, or is the data simply sitting there?
The durable version of an AI or SaaS moat is a compounding system, not a dataset. Look for these signals before concluding a digital business has real staying power.
- Usage-driven learning: does more customer usage measurably improve accuracy, speed, or output quality over time?
- Integration depth: how many systems, workflows, or data pipelines would a customer have to rebuild to leave?
- Contractual and operational switching costs: are there multi-year contracts, custom configurations, or trained internal processes tied to this specific tool?
- Security and compliance posture: does certification or data-handling trust function as a gate that slows competitors from winning regulated customers?
- Partner ecosystem: do third-party integrations or resellers reinforce adoption independent of the core product?
A chatbot wrapped around a general-purpose model with no workflow integration is a feature. A platform embedded in daily decision-making, with years of usage history and five connected systems, is closer to a moat.
Pro Tip: Ask whether a competitor could replicate your data advantage by simply buying or scraping similar data. If yes, the moat lives somewhere else, probably in the workflow.
Common pitfalls and analyst errors when diagnosing moats
Most moat misdiagnoses trace back to a handful of recurring mistakes, and each has a straightforward fix.
- Single-year ROIC misreads: a strong year gets mistaken for a durable advantage. Fix it by requiring a five-plus year spread before drawing any conclusion, and favor economic profit over a one-year ROIC snapshot for capital-light businesses, as McKinsey’s capital-light research recommends.
- Confusing growth with defensibility: a company growing 40% a year can still have no moat at all if that growth comes from price cuts or unsustainable subsidies. Fix it by separating the growth-rate question from the moat question entirely and testing each on its own evidence.
- Overreliance on internal claims: management’s description of its own advantage is not evidence. Fix it by triangulating with external, market-back data, win rates, customer surveys, retention cohorts, rather than taking a pitch deck at face value.
- Treating moat existence and moat magnitude as the same question: a real mechanism can still produce a small, short-lived advantage. Morgan Stanley’s research on measuring the moat frames this as two separate axes, the size of the ROIC-WACC spread and how long it can be sustained, both of which need their own evidence.
Turning moat analysis into decisions: resourcing and portfolio choices
A moat rating is only useful if it changes what you do with capital. Map the result of your analysis to one of four concrete resource rules rather than filing it away as an academic exercise.
- Invest more: a wide moat with a positive trend and strong reinvestment economics justifies aggressive capital deployment, new markets, new product lines, bolt-on acquisitions.
- Defend: a stable, narrow moat warrants spending to protect the mechanism, deepen switching costs, extend contracts, reinforce the brand, without necessarily expanding scope.
- Harvest: a moat with a negative trend but still-positive spread suggests extracting cash while the advantage lasts rather than reinvesting heavily for growth.
- Exit or reallocate: no moat, or a spread that has gone negative, is a signal to redirect capital elsewhere rather than continuing to fund a business that destroys value.
These rules also change how you should value a business. A wide, durable moat supports a longer explicit forecast period and a higher terminal value, while a narrow or eroding moat calls for a shorter horizon and more conservative terminal assumptions. McKinsey’s study of retail outperformers found that 63% of top performers improved at least two of three metrics, growth, margin, and capital efficiency, and tied those gains to validated competitive-advantage analysis that directed where they spent on R&D and new markets rather than spreading resources evenly across the portfolio.
How The operationalization of moat analysis can be facilitated by platforms providing scorecard and workflow templates
Running this workflow by hand, pulling win rates, tracking competitor pricing moves, monitoring retention signals, takes most strategy teams weeks of manual research before they even reach the financial test. We built our competitive intelligence tracking to compress that collection phase so the analysis gets done instead of postponed.
A moat scorecard template generally follows the structure outlined above: mechanism, evidence, financial test, trend, and recommendation, preferably as a one-page artifact rather than a sprawling deck.
- Mechanism: pulled from our strategy library’s framework definitions for the five moat sources.
- Evidence: sourced from automated competitor tracking, win-loss signals, and pricing moves.
- Financial test: ROIC, WACC, and EP calculations run against the peer set you define.
- Trend and recommendation: a rating plus the resource rule, invest, defend, harvest, or exit, that follows from it.
A typical four to six week verification cycle on our platform runs competitor tracking continuously, surfaces pricing and product changes as they happen, and compiles them into the kind of briefing you can see in our sample intelligence briefing.
| Workflow step | What Blue Prysm provides |
|---|---|
| Market-back evidence | Automated competitor tracking and pricing signals |
| Financial persistence test | Strategy framework templates for ROIC and EP modeling |
| Trend rating and scorecard | One-page output usable in board or investment discussions |
For teams that want a guided version of this process, our AI Operational Audit service pairs the platform’s data with a structured review of your specific moat claims.
Near-term moat dynamics and executive priorities
AI is compressing product-level advantages faster than most leadership teams expect, which means the moats worth defending increasingly live in workflow integration and usage-driven learning rather than in any single feature. Executives should prioritize systems that compound with use, measurable retention and switching-cost KPIs, and a recurring review cadence rather than a one-time moat assessment filed away after a board meeting.
FAQ
What is Warren Buffett’s economic moat?
Warren Buffett popularized “economic moat” as shorthand for a durable competitive advantage that protects a company’s profits from competitors over the long run, the same concept Morningstar’s EconomicMoat framework formalized into five measurable sources. The core idea is that a moat lets a business sustain returns above its cost of capital for years rather than quarters.
Can you legally have a moat?
Yes, several moat sources are explicitly legal protections, including patents, regulatory licenses, and exclusive contracts, all of which fall under the intangible assets category in standard moat taxonomy. Other moat sources, like network effects or switching costs, arise from market structure and customer behavior rather than legal exclusivity.
What is a competitive market analysis?
A competitive market analysis evaluates a company’s position relative to rivals across pricing, product, customer retention, and market share, and it typically feeds into a moat analysis as the evidence layer that supports or undermines a specific mechanism. Tools like automated competitor tracking make this evidence collection continuous rather than a one-time snapshot.
What is Apple’s moat?
Apple is commonly cited as having multiple reinforcing moat sources, including brand intangible assets, ecosystem-driven switching costs, and scale-based cost advantages in hardware production. Any specific moat rating or ROIC spread for a named company should come from your own financial testing of its public filings rather than a generic label.
What is the difference between a moat and a general competitive advantage?
A competitive advantage can be temporary, a pricing promotion or a short-term feature edge, while a moat specifically refers to an advantage shown to persist across multiple years of ROIC above WACC. The distinction matters because only a persistent spread justifies long-horizon capital allocation decisions.
Sources
An economic moat is a structural barrier that lets a business keep earning returns above its cost of capital longer than competitors would otherwise allow. Morningstar’s framework identifies five sources that produce this effect, and knowing which one applies to a given business changes how you test it.
- Which metrics really drive total returns to shareholders? — McKinsey
- To scale you need a moat — Wharton
Morningstar also rates duration: a wide moat is expected to protect excess returns for more than 20 years, a narrow moat for 10 to 20 years, and no moat means the advantage is likely to erode within a decade. That time horizon matters more than most analysts give it credit for. A company with a real but short-lived advantage deserves a very different valuation multiple than one with a 20-year runway, even if both show identical ROIC today.